For Buyers In Short
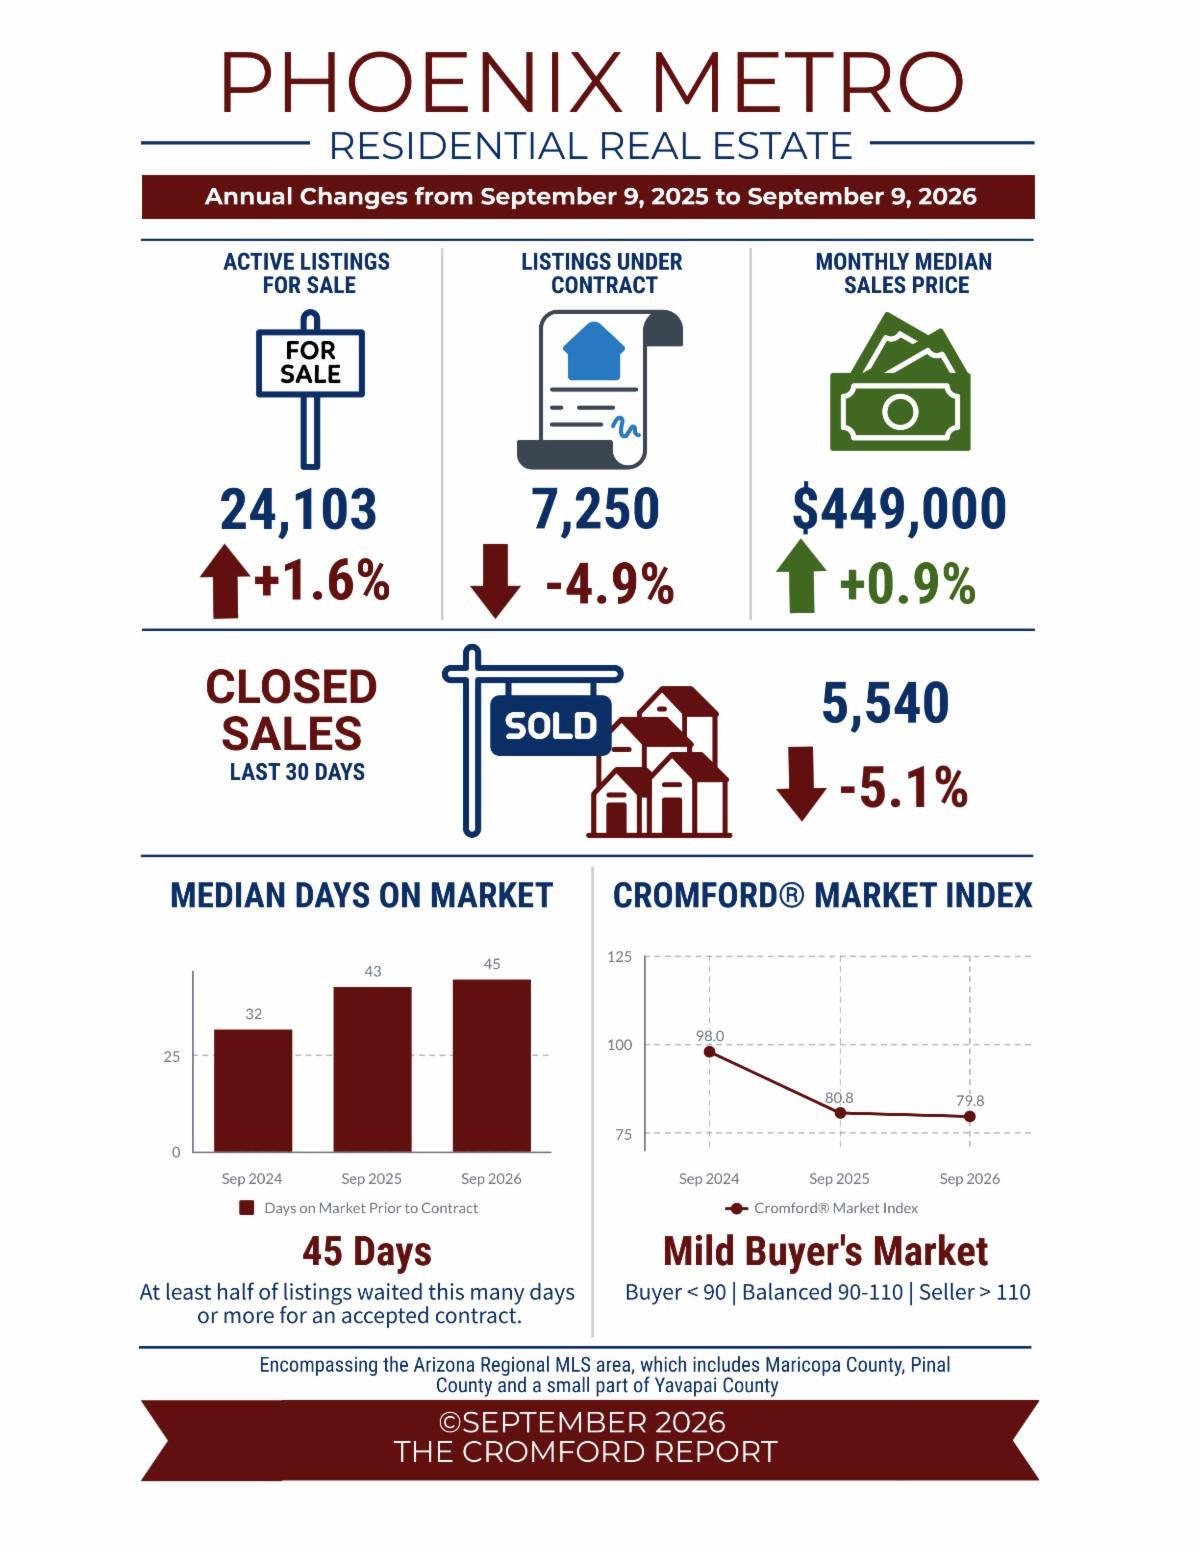
The best description for the housing market vibe this month is disappointment. Average mortgage rates are front and center again, and not in a good way. Home values didn’t crash in 2023 or 2024 when rates were routinely over 7.25%, and market indicators do not support a crash in 2026. However, they may glide with less demand. Ironically, it’s not the rate itself that has caused such a sharp pause in buyer activity, because more homes sold in previous years with the same or higher rates. It’s the volatility of the rate. Buyers typically pause when the rate is actively rising or actively falling, waiting for it to find stability. This pause provides a window of opportunity for those buyers who can shoulder a higher payment temporarily and negotiate a better deal on the price or terms of their purchase. When rates decline again, they may refinance their home and enjoy a lower payment. |
For Sellers In Short
It’s not uncommon to see a median of 50-60 days on market prior to an accepted contract in the 4th quarter. October is a very popular month for new listings, especially in luxury and retirement communities as the temperatures drop, but it doesn’t always coincide with a boost in demand. Buyers have consistently negotiated around 97-97.5% of the last list price for nearly 2 years, so the closer sellers can get to where the buyers believe the price should be, the faster they will get a contract close to asking price. |
OUR TAKE
Home prices in Greater Phoenix have barely moved this year, but the payment on those homes hasn't held nearly as still. The numbers above show why: a jump from 6.75% to 7.24% in two weeks is enough to stall almost anyone, not because the extra money in a payment per month makes a home unaffordable, but because nobody wants to commit to a moving target.
Still, sellers offering incentives, seller-paid closing costs, temporary buydowns, are finding buyers. Nearly 6 in 10 August sales included one.
Worth factoring in too: it's not just the mortgage payment that's moved. Arizona home insurance premiums climbed 71% between 2020 and 2025, far outpacing inflation, though that pace has slowed to just 3.6% this year. It's one more line item buyers should budget for and sellers should expect buyers to ask about.
For buyers: if you can handle today's payment, this is a real window to negotiate on price or terms, with a refinance likely somewhere down the road once rates settle. Buyers who bought at 8% in 2023 were refinancing at 6.1% within a year.
Bottom line: It's a market that rewards patience for buyers and realism for sellers.
Commentary written by Tina Tamboer, Senior Housing Analyst with The Cromford Report
©2026 Cromford Associates LLC and Tamboer Consulting LLC
Did you enjoy this blog? Sign up for our E-News to have inspiration and information sent directly to your inbox!
Subscribe to our E-News!
About Mattisinko Group | Scottsdale, Arizona
Rob and Dani are dedicated to educating and guiding you toward wise decisions. Armed with in-depth market knowledge, pricing expertise, custom marketing strategies, and sharp negotiation skills, this team can help you reach your real estate and lifestyle goals. Call 480-REALTOR (732-5867).